Category: Blog

  • Design Your Own Super Adventure

    Design Your Own Super Adventure

    A popular series of books originally published over a twenty-year period was the ‘Choose Your Own Adventure’ series. As the name suggested, the reader could actually decide what the characters did at key moments in the story. They could choose (to a certain extent) how the adventure played out and how the story ended.

    Many people treat their superannuation like the traditional story book, believing that their employer pays the contributions and someone else looks after the investments, and that’s how the story goes until the end of their working life.

    But the reality is that superannuation funds allow members a level of choice in relation to how the money is invested, which means it can be up to you to create what your retirement adventure might look like.

    What’s Available?

    The first step is to find out what investment options your super fund provides. There may be a couple of options, or there may be many. It all depends on the type of fund you are currently in or are looking to join. Once you know what’s available, you can match it to your personal requirements.

    The fund’s investment menu should show you where your money would be invested based on your selection. Typical characteristics of investment choices within super funds are:

    • Growth – aims for higher growth but accompanied by higher risk;
    • Balanced – aims for reasonable returns and more acceptable risk;
    • Conservative – focuses on lower risk which usually means lower returns;
    • Cash – aims to guarantee your capital but with little or no growth.

    If you don’t choose a super fund, your employer must pay your super into a fund that offers “MySuper” – a default fund that provides only two investment options which depend solely on your age. A default option may be a good strategy, but it is still best to compare it to others rather than accepting it blindly.

    What is Your style?

    There is also no single answer to determining which superannuation options are the best to invest in; there is no “one size fits all”.

    Obviously from time to time shares will perform the best, while at other times it will be more beneficial to have a higher investment in cash or fixed interest. In reality, for most people the right allocation will be somewhere in between. 

    What’s right for you will depend on your age and timeframe; your attitude to fluctuations; and the level of certainty you need to fund your own retirement.

    If you are close to retiring, think about how soon you want to access your super. On the other hand, if you won’t retire for 20 or more years and short-term share market fluctuations don’t bother you, then this will impact on your choice.

    When it comes to your journey before and after retirement, don’t be afraid to choose your own adventure! Contact us to help you enjoy it.  


  • What is Your Concept of Retirement?

    What is Your Concept of Retirement?

    The concept of retirement has changed dramatically over the generations but there remains one constant for most of us planning the end of our working life – to be able to do what we want, when we want. No more alarm clocks, no more commuting and no more demanding bosses! 

    But what do we want more of? Time on the golf course? Unrushed holidays exploring exotic locations? Those are just the basics, however if retirement is looming have you thought about what actually will happen when you stop working? Will you have those choices? 

    Here are a few points to consider; and it’s not just about money.

    Your Wealth

    When preparing to leave the workforce, some people focus so much on never having to face another stressful workday that they overlook many important issues. 

    The first and most obvious focus should be on the income needed to fund the retirement dream. 

    For many people, retirement will give them the first real block of time they have ever had completely to themselves to spend however they please. Some may want to travel, and others may have hobbies they want to immerse themselves. Others may choose to move closer to family or make a ‘sea’ or ‘tree’ change. Some may do all of these things! 

    To make the most of your retirement years, your nest egg must be large enough to allow you to live the life you desire. It would be a shame to have a boring and unfulfilled retirement because you discover too late that you don’t have the means to afford activities that your friends are enjoying.

    Your Health

    Secondly, many people plan for life beyond work assuming that they will remain healthy and vital. For the majority this will prove true, but sadly, others might not be as vigorous as they had hoped. 

    Illness in later years will mean facing additional pharmaceutical and medical expenses. You may incur extra costs from travelling with mobility issues, assuming travel is still manageable. Aged care can be costly, especially where high level care is required. 

    The key point to remember here is that while you are planning for your retirement in a financial sense, you also need to focus on your well-being now to ensure your mind, body and spirit are willing and able to fulfil your retirement hopes and dreams. Balancing both aspects is fundamental to achieving a rewarding lifestyle.

    Your Happiness

    But what is there to do if you find yourself getting bored with so much free time? Well, one option could be to return to the workforce, maybe on a part-time or casual basis. If approaching your former employer or business partner/s is not an option, try something different. Depending on your skillset, you may be able to start a micro-business. All you have to do is get creative when looking at your skills and abilities!

    If you are a retired teacher there are many opportunities, including working as a private tutor or providing after-school assistance, assisting sports teams, or even thesis proofreading for university students. 

    If accounting is your forte, use this skill to help small businesses manage their books. 

    Handy with tools and enjoy fixing things? You could find yourself in demand by those in your area who are working and have no time or skills to do odd jobs themselves. Place an advertisement on your local community board, online, or do a mailbox drop to get started.

    Or, what about volunteer vacationing – “voluntouring”? If you’d like a travel experience with a difference, combine it with volunteer work. Sharing your interests with others or using your skills in a new way could certainly enhance your post-work years.

    There is a plethora of websites that now focus on this latest interest. Just type “voluntourism” into your favourite search engine and be prepared to be amazed.

    Your Identity

    Many people identify themselves according to their job title or profession. For this reason, retirement can leave you feeling like a piece of you is missing. But retirement can be a terrific opportunity to give up that old identity and re-invent a new you. 

    You can be a grandparent, sports enthusiast, volunteer, book club president—the sky’s the limit!

    In many ways, re-inventing yourself as a retiree can be as challenging as being a success in your previous vocation. The key is to establish your priorities, set goals that work for you, and keep going until you reach them. Remember though to keep it fun. 

    Have you Planned Your First Step?

    If all this sounds exciting, don’t forget the first step is to get your retirement funding in order. Come and talk to us sooner rather than later. Once that is done, you can start looking forward to what should be the best years of your life.  


  • Taking Care of Business

    Taking Care of Business

    Owning a business has its distinct advantages. Choosing your work hours and being able to make decisions for your own future are just two, but this higher level of freedom takes a back seat when things go wrong… and as any business owner knows, things can and do go wrong just like in any other pursuit in life. 

    Smart business owners plan ahead for even the most unexpected threats but as times change, these threats come in different forms. We’ve highlighted a few in this article with suggestions on how to deal with them before they affect your hard-earned freedom.

    Protection Against Fraud

    Cybercrime has hit the world by storm. The most common being “ransomware” attacks whereby tech-savvy criminals access business computers to plant malicious programs that shut down entire systems until a ransom is paid. Governments around the world are fighting this battle on a daily basis. All have a key focus on educating people on what to do to protect themselves and what action to take if attacked. 

    With this increased awareness, many business owners are taking precautions to protect their systems from external attack, but what happens when the infiltrator comes from inside? 

    If you employ staff, don’t rely on glowing CVs. With so many former “star” employees now sitting in jail cells for committing fraud in the workplace, employee screening is now an integral part of the hiring process. Many independent services are available and cover everything from employment history checks through to full police checks. In addition, specialist insurance policies provide protection against “white collar crime”. Paying a little bit more for these services not only brings peace of mind but another level of freedom.

    Who Can You Rely On?

    It’s crucial that all business owners have appropriate personal and business insurance cover if they are unable to work due to illness or an accident, but that will only look after the financial costs – who will manage business operations if you can’t? 

    If you are the only person in your business (and over 60% of businesses in Australia – almost 1.5 million – do not employ staff), it is imperative to have all of your operations and procedures clearly documented. But it doesn’t stop there – if something happened to you, who would know where those documents are and how to access them? A wife or husband may have a general understanding of a business, but if they have to step into it on a full-time daily basis, will they know how it all works? Set aside some time to take them through your procedures and show them where key material is located. 

    If you don’t have a partner who can step in, ask a trusted friend or colleague if they could look after the basics to keep your business operating in the short term. Most importantly, make sure they know where your procedures and important documents are located now, not when you might be unable to tell them.

    Having a good contingency plan to cover your absence is vital – knowing that someone will be able to pick up the reins will mean the difference between keeping your business operating and having to close it down.

    Disaster Strikes!

    What would happen if a disaster – natural or man-made – struck your business? Would you be ready? How long would it take to get back on your feet? Would you fully recover? Here are four key areas to address to help maintain your freedom:

    1. A good business disaster recovery plan must be documented (not just in your head) and copies provided to all key personnel. Everyone should know what to do in the event…
    2. Business interruption insurance cover can cover major outlays such as setting up new premises or re-establishing computer equipment. 
    3. Traditional business insurance policies may not cover losses related to cyber-attacks and given the snowballing risks, Cyber Insurance is becoming another essential for business owners.
    4. Important original business documents such as mortgage papers, trust deeds, corporate registers, and signed agreements should be kept securely off-site, with scanned copies backed up in a separate location. 
    5. The Australian Cyber Security Centre (ACSC) reports that cybercriminals sometimes increased the ransomware price when they discovered a business did not have backups. All computer files should be backed up daily with a current copy located off-site. If you don’t have a separate location to store backed up files, install a fire-proof safe to protect them. 

    Having read this you might be thinking it’s all too hard, but just take one step at a time and talk to a professional adviser who can help you protect your business – and your freedom.


  • When Love Blossoms Later in Life

    When Love Blossoms Later in Life

    Falling in love is a magical and wondrous experience, but once the heart flutters have settled a little and two people move towards a more serious relationship, various challenges may need to be addressed. Many of these challenges can be easily resolved when we’re young and carefree, but what happens when Cupid appears – or reappears – later in life? 

    Unlike earlier relationships, when love blossoms late in life careers have slowed down or ceased, the children have left home, and health and fitness may not be what it had been, meaning that a ‘lifetime’ of togetherness may not be as long as first anticipated.

    From a less romantic perspective, the financial implications of beginning a relationship at this time of life are serious and need to be considered carefully. In many circumstances, the couple’s children are adults whose voices want to be heard, particularly in relation to matters of the will. Parents who re-partner without considering the broader families and important people who took part in their life journey are at risk of unknowingly creating negative repercussions. For example, ‘new’ partners who pass on their estates only to each other, leaving at least one of the couples’ children with nothing while the other partner’s children inherit all, can cause long-term hurt and pain. In many cases, this act may not be intentional.

    Another financial aspect unique to this stage of life emerges when there is a high level of financial disparity between the two partners. While one partner has accumulated a lot of wealth, the other may have not. Questions are then raised in regard to how finances are distributed between the couple while they are alive and after one or both die.

    Other implications can relate to health issues. They include questions such as who would be the primary carer for a sick partner? The sick partner’s children, or the new spouse? What are the role divisions between the children, other family members and the spouse?

    Take Advice and Make Plan

    Whilst every situation will be different, here are some guidelines for addressing the unique features of financial planning in later life. In particular, emphasis is given to the inter-generational and multi-stakeholder aspects of this relationship.

    1: Involve everyone long before the will is read

    For many years it was customary to not involve children and other relevant stakeholders in formulating a Will. History books are filled with disputes and hurt feelings over Wills that were read leaving the beneficiaries astonished and devastated over the deceased’s final decisions. Don’t wait until it is too late. Financial matters that can have serious impacts on the future lives of your loved ones need to be discussed well in advance with all relevant stakeholders. Preferably before your Will is signed and sealed. 

    2: Plan for the present with a view to the future

    New relationships require new financial arrangements. For example, if buying a property together, what are the consequences of sharing a dwelling?

    Below are some examples:

    A. When purchasing property consider the estate planning implications

    When couples decide to purchase a property jointly it has immediate consequences for the beneficiaries of the couple following the death of a partner. This issue can be addressed by registering the property owners as “tenants-in-common”, ensuring that the deceased’s beneficiaries will inherit their appropriate share of the property. Couples may give themselves a “life interest” in the property to allow each to remain living there after their partner’s death. The implication of this for the beneficiaries is that they will only be allowed to receive their inheritance after both partners have died. 

    B. Potential age pension changes

    An age pension payment will change as a consequence of living together. This can occur when one partner is still working and the other is retired and receiving the pension; or both partners have previously been eligible for a single pension. The difference between the age pensions for a single person is $952.70 per fortnight compared to $1,436.20 as a combined couple – $483.50 less per fortnight.

    Case study: Moving In Together

    Brian and Elizabeth recently moved in together. Brian is semi-retired and received a part-age pension from Centrelink. Elizabeth is still working full-time and earning a salary. When Brian informed Centrelink of his new living arrangement he had to provide detailed information about Elizabeth’s financial circumstances. Based on their combined assets and income, Centrelink assessed that Brian was no longer eligible for any pension, and his payments stopped. As the Centrelink assessment was completed weeks after he had moved in with Elizabeth, Brian had to repay Centrelink the overpaid pension amount. 

    C. Superannuation beneficiaries need to be reviewed

    If new partners are members of a superannuation fund they need to review their instructions regarding which beneficiaries receive a death benefit. For example, if a couple has specified a “non-binding” nomination for their beneficiaries, this will be invalid now that they have partnered. This is a complex area of estate planning that requires personalised advice.

    3: Design financial agreements suited to the partners’ financial circumstances

    A happy relationship is a transparent one, particularly when it comes to money. A good start is to draw up a personal “balance sheet” listing the values of all assets each person owns (eg. property, superannuation, car, bank accounts, etc). All debts and liabilities, such as an outstanding mortgage, personal loans and credit card balances, should also be included. 

    After both partners are aware of the other’s current financial situation, and if appropriate, a “Binding Financial Agreement” could be considered. This is a legal document that sets out how their property and assets would be divided were they to separate. This is particularly appropriate when there is a high level of financial disparity between partners.

    4: Plan health care prudently

    Growing old together involves increasing health costs and risks of illness. It is recommended that the partners review their health insurances and redesign them to fit the new life arrangements. Redesigning may also reduce premium costs. 

    Health care plans need to involve relevant family members who may wish to take part in managing care at times of need. Planning in advance could reduce future friction between the cared one’s family and the new spouse regarding treatment strategies and expenses.

    Planning and preparing financially should by no means lessen the excitement of a new love experience, but when addressed properly will allow the newly formed relationship to be a source of growth for the couple and their loved ones, in the present, and into the future.

    It is recommended to discuss these matters with an estate planning lawyer and your financial planner sooner rather than later.
  • What to Do with an Inherited Gift

    What to Do with an Inherited Gift

    When you receive money or a gift from a family member’s or friend’s estate, the last thing you probably think about is tax and insurance. However, you can circumvent future difficulties or financial loss if you attend to a few practical financial issues as soon as possible.

    Let’s Start with CGT

    Determining your capital gains tax (CGT) liability when bequeathed assets are eventually disposed of can be a real headache. To avoid potential problems always determine and document whether the assets were acquired by the deceased before or after 20 September 1985.

    It is a good idea to obtain an accurate valuation as at the date of death if retained assets were acquired before 20 September 1985, because any future CGT liability will be determined by the increase in value from that date (known as the ‘cost base’).

    Also it is important to know how the gifted assets are classified for CGT purposes. Generally these assets will be divided between collectables, personal use assets and other assets. Some special, but limited, CGT exemptions can apply to ‘collectibles’ and ‘personal use’ assets. These exemptions are also based on their ‘cost base’.

    Collectibles vs Personal Use Assets

    Valuations are particularly important for any assets or objects categorised as ‘collectibles’. If the market value of a collectible (including antiques) at the date of death was less than $500 then any capital gain will be disregarded. A similar, but much higher exemption applies to ‘personal use assets’ of up to $10,000.

    ‘Collectables’ are defined as artwork, jewellery, antiques, coins or medallions, rare folios, manuscripts or books, postage stamps or first day covers that are used or kept for personal use or enjoyment.

    ‘Personal use assets’ are non-collectible assets, other than land or buildings, used or kept for the personal use or enjoyment of the deceased. An item of personal furniture would normally fall into this category, unless it is determined to be ‘antique’, for tax purposes. In this latter case it will fall into the ‘collectible’ category.

    When an Antique is Not an Antique

    Unfortunately the word ‘antique’ for the purposes of determining if they should be treated as ‘collectibles’ or simple ‘personal use assets’ is not clearly defined in the Income Tax Acts. However, a tax ruling (TD 1999/40) has been issued to clarify this point. To quote from the tax ruling: ‘An ‘antique’ for the purposes of the Income Tax Assessment Act is to be determined according to ordinary concepts and usages. It is generally recognised that an antique is an object of artistic or historical significance that is of an age exceeding 100 years’.

    The point at which an asset is deemed to be an antique for CGT purposes relates to when it is disposed of, not when it is acquired. For example, this means that if Tom retained a fine piece of furniture that was 96 years old when acquired, it would not be deemed to be an antique at that time (it would merely be a personal use asset). But if he sold the very same piece five years later (when it was 101 years old) it would be deemed to be an ‘antique’, and as such it would be categorised as a ‘collectible’ asset for CGT purposes.

    This business about ‘antiques’ might all seem a bit complicated. However, the key point is that it may be very useful to ascertain the relative age of any old and valuable furniture. You can see that this can have a significant impact on the tax position. As a practical proposition it is often much easier to gather such information (perhaps from the deceased’s records) soon after death, rather than try to determine the age of an antique many years later when you are planning to sell the item.

    Generally, it is not necessary to obtain a valuation for tax purposes, if the deceased acquired an asset on or after 20 September 1985. This is because the ‘cost base’ for the beneficiary will be the same as that of the deceased’s. Similarly the beneficiary is taken to have acquired an item as a collectible or personal use asset. To explain, let’s take our example further. Say Uncle Reg had acquired a rare old book (a collectible) for $2,000 in 1997. Tom, as his beneficiary, would have been gifted a collectible. In future he would use this $2,000 to determine how much gain, and hence how much CGT that will apply, if and when he sold the book.

    You can appreciate that while a valuation at the date of death may not be required, it is still necessary to find out what the ‘inherited’ cost base is for future reference. Again that tends to be easier to do sooner rather than later.

  • The Rise of Ethical Investments

    The Rise of Ethical Investments

    In recent years, ethical investing or socially responsible investing (SRI) has become increasingly popular. Driven by the growth in demand for businesses that are profitable and ethical, along with regulatory frameworks to address challenges such as climate change and modern slavery, there has never been a better time to gain exposure to ethical investments.

    What are Ethical Investments?

    Ethical investments provide exposure to companies with strong environmental, social and corporate governance (ESG) structures and practices. The Responsible Investment Association of Australia estimates there is almost $1 trillion invested in ethical companies and strategies across the country, equating to 44 per cent of the entire $2.24 trillion managed by professional investors in Australia.

    Depending on your risk appetite, there are a range of ways you can invest ethically. You can put capital into an actively or passively managed fund with a focus on ethical investments. Your super fund may also offer investment options that focus on ethical leadership and business practices.

    How to Pick Stocks in Ethical Companies

    The research and analysis process for buying stock in ethical companies is broadly no different from regular stock picking. Analysing the typical indicators of financial strength is essential, including earnings per share, the price-to-earnings ratio and dividend yield. You will, however, need to weigh up whether a company’s approach to ESG aligns with your beliefs around important issues. These issues are typically environmental, societal, and political.

    How to Get into Ethical Investing

    To get into ethical investing, you may place some of your capital into a responsible investment fund which uses ESG and ethics criteria, along with financial performance, to determine which companies are invested into. It’s important to note that the screening criteria for responsible investing are different from those used in strict ethical funds. As a comparison, strict ethical funds screen out specific industries such as energy, mining, gambling, pornography and narcotics as a default. ESG investment funds differ by focusing on stakeholder engagement and shareholder activism to influence change in companies instead of simply divesting or eliminating the option of investing in particular organisations in the first instance.

    Whether you put your money in a fund or decide to pick individual stocks to get started in ethical investing, you need to determine what you’ll look for in potential investments. You may look for companies that are carbon neutral, or those that have initiatives such as planting a certain number of trees each year. There are also more detailed criteria such as the company’s approach to manufacturing which you may assess in your research. You may also choose to invest in funds that are financial vehicles and loan money to, or invest in, ethical businesses.

    Do Your Research to Diversify Your Investments

    Similar to diversifying your portfolio with a range of asset classes, you also need to do your research and thoroughly analyse any potential investments that will provide exposure to ethical companies. To ensure you balance risk effectively, speak to your financial adviser to assess the specific ethical investments that are suitable for your unique situation.

  • Home is Where the Heart is – Please Protect it

    Home is Where the Heart is – Please Protect it

    When you receive money or a gift from a family member’s or friend’s estate, the last thing you probably think about is tax and insurance. However, you can circumvent future difficulties or financial loss if you attend to a few practical financial issues as soon as possible.

    As a direct result of the widespread natural disasters Australia has experienced in recent years, insurance premiums for house and contents have, in many cases, risen dramatically. When faced with these higher costs, many home-owners might be tempted to under-insure their homes or, even worse, not insure at all.

    Your home may be your pride and joy, an asset with a big emotional attachment, but it is also usually the biggest financial commitment you will ever make.

    It therefore makes sound financial sense to insure your home appropriately. Whether you are reviewing your current cover or insuring a new home, here are some tips to help you make the right decisions.

    Identifying Your Needs

    Determining the appropriate level of insurance is a relatively simple process:

    1. Make sure you obtain an up-to-date valuation for your home. Home prices can change significantly over time so it is important to know the current value of your property to enable you to match the insurance cover accordingly. The services of a property valuer could be engaged to obtain a professional expert opinion, or you could contact a couple of real estate agents specialising in your area for their view.

    2. Accurately assess your contents value. While you might not think your ‘stuff’ is worth that much, most people actually have more than they realise. The value of your contents quickly adds up, especially considering the cost of ‘little things’ like your music and movie collection, clothing and kitchen items.

    Many insurance companies have contents checklists on their websites to help make this process easier.

    Complete a contents checklist then take a video of everything. Being able to see what your home and contents look like in detail can help a claims assessor speed up the process. Don’t forget to update it periodically or as you buy/replace larger items.

    After completing your checklist and video, store them securely. A small fireproof safe can be an affordable option; or store them away from your home with a trustworthy friend or relative. 

    3. Take into account whether you live in a known bushfire or flood risk area and consider obtaining a quote for the cost to completely replace your property. A registered builder will be able to provide you with realistic cost options to give a more accurate assessment of cover required.

    4. Appropriately calculate the value of any collectibles or jewellery. Many people have inherited assets or have a special (or very expensive) piece of jewellery. Others may have collections that can turn out to be more valuable than they ever thought possible. 

    Make sure that you obtain a specialist valuation for any items of particular value so your insurance coverage can be adjusted accordingly.

    Finding the Right Insurance Policy 

    Detailed below are some tips to assist you in getting the policy that perfectly suits your personal circumstances.

    • Are there any exclusions? It is said that the devil is always in the detail. Some providers have exclusions that are standard options on the same class of cover with a competitor, so make sure you read the fine print, especially when switching providers.
    • Understand the options available. There are many insurance companies within the Australian marketplace, each offering different types of insurance coverage to suit a variety of needs. Make sure you understand fully what you are covered for before signing up. Not all insurance policies are created equally, even if they are called by a similar name.
    • Are you covered for natural disasters? Damage caused by catastrophic weather events can be subjective so make sure your cover matches the level of risk your home is reasonably likely to face. Some insurance companies only cover natural disasters of certain types in particular areas.
    • Consider additional policy options. For a small additional premium you can add extras to your coverage. For example, many insurers offer cover for alternative accommodation for a set period if your home has to be rebuilt following a disaster.
    • What about renovations? You need to check that your existing policy adequately covers you during any renovation process. And don’t forget to review the policy to cover the increased value of your home after the reno.
    • Does absence affect your policy? Some insurers will decline to cover a home that is unattended on a regular basis or for a prolonged period of time. This is especially relevant if you’re planning to become a Grey Nomad or are often away from home for other reasons.
    • Insuring a rental property. Specialist insurance for landlords may be needed to cover your home for damage or theft if your property is not owner-occupied.
    • Answer all questions accurately. This is crucial because if there are any errors or untruths discovered by the insurer at claims time, it may decline to pay some or all your claim.

    It Won’t Happen to Me…

    It is expected that damaging weather events will cost Australia $33 billion by 2050. Natural disasters such as bushfires, floods and destructive storms are part of life in Australia:

    Bushfires: Property losses are commonly experienced in most Australian states, typically between September and March. The direct cost of the 2019-20 bushfires has been estimated at over $4.4 billion.

    Floods: Unprecedented wide scale and repetitive flooding in recent years proves that no single area of Australia is totally safe from these disasters. The 2011 floods in Queensland that also affected New South Wales, still rank as one of the costliest disasters with the economic loss valued at $6 billion.

    Cyclones and Storms: Cyclones are common in northern Australia, especially between December and April, and over the decades have destroyed entire towns. However, in recent years, severe storms nation-wide have caused damage on a more regular basis than cyclones.

    Consider Speaking to an Insurance Expert

    If personally navigating your coverage options isn’t for you, ask for specialist help.
    If your home is where the heart is, it’s crucial to protect it from potential harm.

  • Separation Planning: An adviser’s Perspective

    Separation Planning: An adviser’s Perspective

    Few client meetings have been as challenging. After years of being happily married, Sarah and her husband decided to separate, and the story of her acrimonious divorce was certainly distressing.

    It started with a chance meeting, where in passing, Sarah mentioned the divorce. She assured me she’d had enough of advisers for a while and just wanted some time out. I insisted we meet as quickly as possible.

    The first step was to sort out her will. Again, Sarah said she never wanted to speak to another solicitor again, but this quickly changed when I explained that if something happened to her today, all her assets would go to her ex-husband.

    We also needed to update her superannuation. The binding nomination she had put in place, again leaving everything to her ex, needed to be changed to stop this flow of money, which would otherwise bypass her will and go directly to her husband.

    I suggested Sarah think about putting in place a power of attorney so someone could step in and handle her affairs if she could suddenly no longer do this herself as well as think about appointing a medical power of attorney.

    She needed to make provisions for her three children. While her ex-husband insisted, he’d continue in their lives, this could easily change in the future, particularly if he were to meet someone new.

    Sarah had retained the family home but needed to re-mortgage it to buy out her ex-husband. As a successful professional in her own right, she could afford to do this but only just. A new family budget was needed, and she would have to stick to it, at least for the next few years.

    So far, Sarah had been agreeable to my suggestions, but then I turned the conversation to two other key areas. To retain the family home, Sarah had agreed to give part of her superannuation to her ex-husband.

  • Uncovering the Iceberg of Financial Advice

    Uncovering the Iceberg of Financial Advice

    We can all agree that the costs of providing financial advice have risen significantly over recent years. An article from Rod Bertino at Business Health mentioned average ongoing fees at $3,558 per annum in the current advice landscape.

    I see many practices going through the exercise of re-evaluating their cost-to-serve, factoring in current overheads and a reasonable profit margin, with considerable gaps often found between current fees charged and what should be charged after the cost-to-serve analysis.

    For mature businesses with long term clients, this seems to be a common problem, especially when presenting fee increases to these long term clients. The issue has, however, also arisen when looking at making acquisitions involving clients with annual fees.

    The issue of value in ongoing advice should be addressed as part of the overall fee review project. And this is where the illustration of the iceberg comes in.

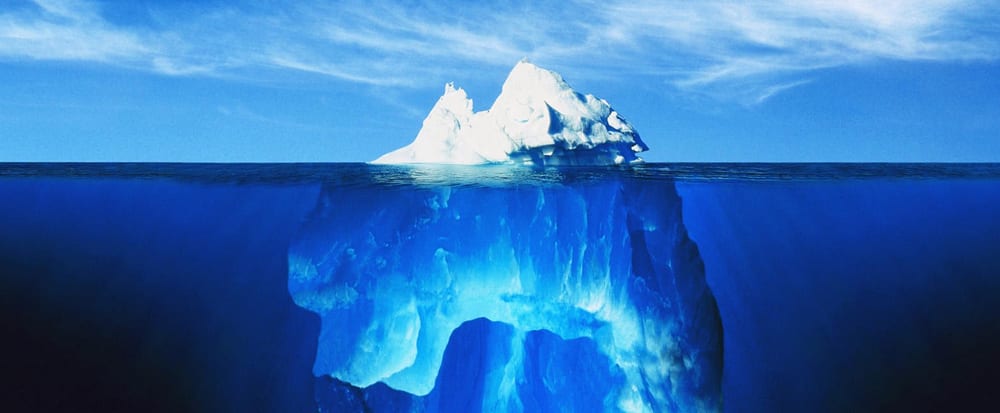
    The Iceberg Principle (or Iceberg Theory) suggests that we cannot see or detect most of a situation’s data. The theory applies to systems and problems too. As with an iceberg, only its tip is visible, while the bulk is below the water’s surface, invisible.

    It is interesting to look at the cost-to-serve analysis and see the small number of client-facing hours during a year versus the overall hours spent providing services to clients.

    In examples I have recently viewed, only 10% of the total hours served on a client’s work were face-to-face. It is clear there are many tasks that clients do not see over a year, yet that are still providing value.

    The list of items below the Iceberg waterline is quite extensive, including:

    • Review of goals and implications;
    • Record of Advice;
    • Supporting documentation and facilitating the implementation of any additional advice provided; 
    • Review portfolio management;
    • Review debt and insurance;
    • Centrelink;
    • Effect of legislation changes; and
    • Administration.

    When presented with all the information, clients can make their own decision regarding the price they are prepared to pay for ongoing advice and the peace of mind it brings. I have many stories where clients have surprised their financial planner with determination to maintain an ongoing relationship at a higher price.

    I believe some of the cost-to-serve issues lie with financial planners underestimating their value and unable to position their fees appropriately.

    Cost-to-serve analysis like this requires help from a financial business specialist, who has seen what works in many different practices.

    If this story resonates with you, why not give me a call? I help financial planners improve their business life.

  • Australia’s Reliance on China

    Australia’s Reliance on China

    In 2007 China displaced Japan as Australia’s largest trading partner. In 2009 it became Australia’s largest export market, and in 2017-2018 we sold A$123.3 billion worth of goods and services to China – 30.6% of our total exports. In comparison Japan, still our second most important market, only took 12.7% of our exports.

    On the flip side China supplied us with 18% of our imports worth A$71.3 billion. Our total economy, as measured by GDP, was worth around A$1.9 trillion at the time, so our two-way China trade made up about 10% of our economic activity. That may not make us totally reliant on China for our economic health, but any major disruption to that trade means Australia will have many billions of dollars less to run our schools and hospitals, pay pensions and wages, and to maintain our high standard of living.

    Should We be Looking to Other Markets?

    In times of smooth sailing a high dependence on one trading partner may not be a cause of great concern. However there are many events that can disrupt trade, from natural disasters and pandemics to political tensions. In such times having a range of export markets helps to reduce the impact of interruptions to trade with one partner.

    Achieving greater diversity of export markets is easier said than done however, particularly when seeking to replace demand from what is the biggest market for many of our goods and services. For example, China takes 100% of the nickel ore, 95% of the timber and 83% of the iron ore that we export. It also takes time to build trust and develop the personal relationships that underpin trade.

    Looking at the big picture, China accounts for around 16% of global GDP. That leaves 84% in which to seek out new markets.

    When Relationships Sour

    The political and diplomatic relationship between China and Australia might be described as ‘challenging’ at present, with trade being used as a weapon of influence. Still, there’s more to Australia’s economic story than China, and many Australians may not experience much fallout from these trade tensions. They may even benefit from a surfeit of cheaper lobsters! On the other hand, and in the worst case, the farmers, winemakers, coal miners and timber workers who have seen the fruits of their labour hit with huge tariffs or denied entry into China face potentially catastrophic losses. This would place a general drag on the economy, potentially spark a recession and lead to an increase in unemployment.

    The Importance of Trade

    Nations engage in trade because it creates wealth. Our iron ore and coal helped to modernise China, build its infrastructure and allow it to make a huge range of manufactured goods, many of which we then import at much lower cost than we could make them for here.

    In support of trade, Australia is currently a party to 14 free trade agreements (FTAs), including one with China. Much of the focus of these agreements is to reduce or remove the tariffs that increase the cost of our goods in our export markets, and where possible eliminate other barriers to trade. For example, the China-Australia Free Trade Agreement provides Australian businesses with better access to Chinese markets for legal, education, financial and tourism services, amongst others.

    Perhaps the most comprehensive FTA is the Australia-New Zealand Closer Economic Relations Trade Agreement. Aside from eliminating all tariffs between the two countries, it also harmonises food standards, which minimises regulatory red tape, and removes impediments to the movement of skilled workers between the two countries. Unfortunately, as the recipient of just 3.6% of our exports, it will take a lot of New Zealands to significantly reduce our reliance on China.